Acquisition and light rehab
A purchase with cosmetic or limited repairs where the budget, contractor plan, and marketable exit still need support.
Purchase and renovation financing
Build a review-ready request around the acquisition, renovation budget, project schedule, capital contribution, and a credible sale or refinance exit.
The essential answer
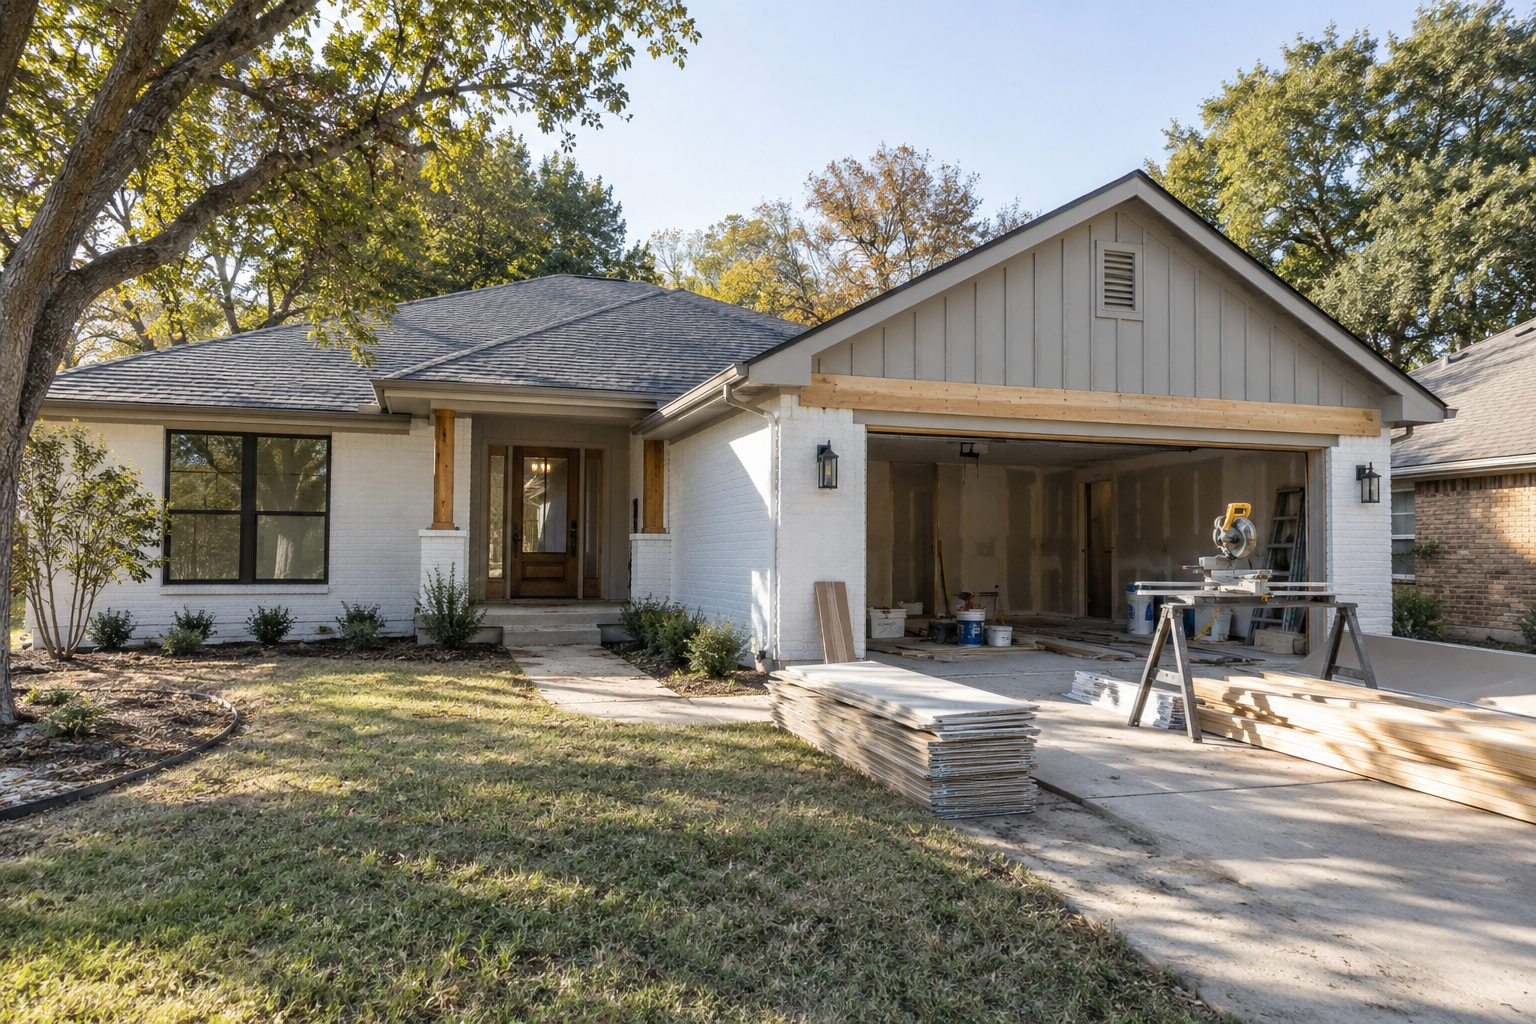
A useful request connects five parts: the acquisition basis, the existing property condition, the proposed scope of work, the capital needed to execute, and the event expected to repay the financing. Those facts should support one another. An ambitious resale target cannot compensate for a vague budget, and a detailed scope cannot compensate for an unrealistic timeline or an unsupported exit.
Fix and flip loans are commonly researched by investors who need business-purpose capital for a property that may not fit conventional financing before renovation. Depending on the actual program, proceeds may address the purchase, eligible rehabilitation costs, or an existing investment-property loan. Availability, structure, draws, pricing, leverage, and documentation remain provider-specific.
Common project paths
These scenarios can share a search phrase while requiring different budgets, teams, contingencies, documentation, and exits.
A purchase with cosmetic or limited repairs where the budget, contractor plan, and marketable exit still need support.
A broader scope involving systems, layout, structural work, permits, or a longer schedule and larger contingency.
A recently acquired investment property where the source of purchase funds, seasoning, completed work, current value, and requested proceeds matter.
An existing project needing additional capital, with careful review of liens, work completed, remaining budget, cost overruns, and revised exit.
A renovation followed by lease-up and permanent rental financing, supported by realistic stabilized value, rent, expenses, and timing.
A resale strategy supported by comparable properties, total basis, carrying costs, selling costs, schedule, and a margin that can absorb surprises.
First-pass review
These are preparation categories, not universal qualification criteria. Exact requirements come from the professional reviewing the actual deal.
Address, contract price, current use and occupancy, title, access, condition, and any known physical or legal issue.
Line-item work, quantities, bids, labor and material assumptions, permits, soft costs, contingency, and costs already paid.
Relevant projects, contractor relationship, licenses where applicable, project management, insurance, and responsibility for each stage.
Requested loan, earnest money, borrower contribution, funds to close, renovation cash flow, reserves, and the treatment of any existing debt.
Closing target, permit timing, construction sequence, inspection milestones, draw reimbursement mechanics, and room for delay.
Sale or refinance support, target completion, comparable evidence, carrying period, backup plan, and the effect of lower value or slower execution.
Fix and flip calculator
Enter the purchase, renovation budget, requested loan, ARV, rate, points, and term. The result is an educational planning model—not a quote or qualification.
Live planning estimate
Defaults are illustrative, not current rates or program limits. Assumes the full requested balance remains outstanding for the entire term and interest is paid monthly. Principal is still due at repayment. Actual draw schedules can change interest. Excludes appraisal, title, legal, escrow, extension, servicing, and other costs. Ratios are unavailable when their cost or value denominator is zero. Planning estimate only—not a quote, approval, commitment, or complete closing-cost calculation.
Structure without teaser promises
Rates and thresholds change. This page does not publish a universal rate, minimum score, maximum leverage, draw schedule, or guaranteed closing time.
Potential fit
Pause first
Fix and flip questions
The goal is a useful first conversation, followed by only the documents relevant to the real scenario.
Fix and flip financing is generally short-term, business-purpose real estate financing used to acquire, renovate, and sell or refinance an investment property. The complete review can include the purchase, current condition, renovation scope, budget, leverage, experience, liquidity, timeline, value support, and exit.
Some programs may finance part of an approved renovation budget through controlled draws, while others structure proceeds differently. The provider must confirm eligible costs, borrower contribution, holdbacks, inspections, draw timing, and the conditions for releasing funds.
After-repair value, or ARV, is an opinion of the property's potential value after the defined work is completed. It is not the owner's target resale price. A valuation professional and the receiving provider determine how value is supported and used.
There is no responsible universal promise. Timing depends on title, valuation, property condition, borrower and entity documents, budget quality, insurance, provider capacity, and whether the request arrives complete.
Experience can affect structure, leverage, documentation, reserves, or eligibility, but requirements vary. A first project may still be worth discussing when the team, scope, capital, contingency, and exit are well supported.
The initial plan should include a realistic contingency and explain who can cover overruns. A draw facility is not an unlimited budget, and unapproved changes or cost increases can require additional borrower funds.
A refinance can be a valid exit only when the projected stabilized value, rent, occupancy, property condition, borrower profile, and permanent financing assumptions are realistic. The next loan is not guaranteed by the short-term financing.
No. It uses the values you enter to illustrate project cost, cash gap, interest, points, LTC, and loan-to-ARV. It does not model every fee or draw schedule and does not represent a provider decision.
Editorial and role disclosure
Veldinext Capital is presented as an intake and routing platform, not a bank or direct lender. A submitted request does not guarantee acceptance, financing, a valuation, draw approval, terms, timing, or project outcome.
Program facts, geographic availability, licensing, disclosures, lead-routing permission, and compensation compliance must be confirmed with the receiving professional before public indexing and live lead delivery.